39 zero coupon bonds duration
Quant Bonds - Between Coupon Dates - BetterSolutions.com Investor 1 buys a bond from Investor 2, 10 days before a coupon is paid Investor 1 will receive the entire coupon Investor 1 must pay Investor 2 most of the accrued interest. Important There is an inverse relationship between price and yield. The higher the yield, the lower the price. Bloomberg screen - DCX © 2022 Better Solutions Limited. Valuation Of Zero Coupon Bonds - Otosection A 5 year zero coupon bond is issued with a face value of $100 and a rate of 6%. looking at the formula, $100 would be f, 6% would be r, and t would be 5 years. after solving the equation, the original price or value would be $74.73. after 5 years, the bond could then be redeemed for the $100 face value.
calculator.me › savings › zero-coupon-bondsZero Coupon Bond Value Calculator: Calculate Price, Yield to ... Economist Gary Shilling mentioned holders of 30-year zero-coupon bonds purchased in the early 1980s outperformed the S&P 500 with dividends reinvested by 500% over the subsequent 30-years as interest rates fell from around 14.6% to around 3%. I started investing in 30 Year zero coupon treasuries. Now, zero coupon bonds don't pay any interest ...

Zero coupon bonds duration
Basics Of Bonds - Maturity, Coupons And Yield - InCharge Debt Solutions To calculate the current yield for a bond with a coupon yield of 4.5 percent trading at 103 ($1,030), divide 4.5 by 103 and multiply the total by 100. You get a current yield of 4.37 percent. Say you check the bond's price later and it's trading at 101 ($1,010). The current yield has changed. Divide 4.5 by the new price, 101. › investors › insightsThe One-Minute Guide to Zero Coupon Bonds | FINRA.org Like virtually all bonds, zero-coupon bonds are subject to interest-rate risk if you sell before maturity. If interest rates rise, the value of your zero-coupon bond on the secondary market will likely fall. Long-term zeros can be particularly sensitive to changes in interest rates, exposing them to what is known as duration risk. Also, zeros ... How to Invest in Bonds - The Motley Fool There are two ways to make money by investing in bonds. The first is to hold those bonds until their maturity date and collect interest payments on them. Bond interest is usually paid twice a year ...
Zero coupon bonds duration. Long Term Government Bond ETF List - ETF Database Long Term Government Bond ETFs provide investors with exposure to the long side of the U.S. bond market. These funds focus on debt sponsored by the U.S. government or its agencies and can include Treasuries, MBS, TIPS or other debt. Long-term bonds generally have maturities longer than 10 years. SPDR Bloomberg 1-3 Month T-Bill ETF - ETF Database This popular ETF offers exposure to the ultrashort end of the maturity curve, focusing on zero coupon U.S. T-Bills with less than three months until maturity. BIL is extremely light on both interest rate risk and credit risk, and as such will generally deliver a very low expected return. BIL can be a great safe haven to park assets in volatile markets, but won't deliver much in the way of ... Domestic bonds: SG Issuer, 0% 8apr2024, EUR (3749D, Structured ... Domestic bonds: SG Issuer, 0% 8apr2024, EUR (3749D, Structured) FR0011607837 Download Copy to clipboard Guaranteed, Structured product, Zero-coupon bonds, Senior Unsecured Status Outstanding Amount 250,000,000 EUR Placement *** Redemption (put/call option) *** (-) ACI on No data Country of risk France Current coupon - Price - Yield / Duration - Understanding Corporate Bonds | PIMCO Glossary. Coupon: The interest payments a bondholder receives until the bond matures.; Corporate bond: Debt instrument issued by a company, distinct from one issued by a government or government agency.; Credit risk: The risk of loss of principal or loss of coupon payments stemming from a borrower's failure to repay a loan or otherwise meet a contractual obligation.
iShares 0-5 Year Investment Grade Corporate Bond ETF | SLQD Effective Duration as of Sep 01, 2022 2.35 yrs Convexity as of Sep 01, 2022 0.07 Option Adjusted Spread as of Sep 01, 2022 82.24 bps This information must be preceded or accompanied by a current prospectus. For standardized performance, please see the Performance section above. Sustainability Characteristics What are Bonds? | Definition & Types | Beginner's Guide Zero-coupon bonds (Z-bonds) type bonds do not make periodic coupon payments and instead are issued at a discount to their par value and repaid the total face value at maturity. For example, U.S. Treasury bills are zero-coupon bonds. Convertible Bonds Quant Bonds - Asset Swap Spread - BetterSolutions.com Uses the Zero Coupon Yield curve By combining the two you can change the coupon payments to either fixed or floating. This is the yield of the bond minus the swap rate for the corresponding maturity swap A fixed-rate bond will be combined with an interest rate swap in which the bond holder pays a fixed coupon and receives a floating coupon. Here's What Happens When a Bond Is Called - Investopedia Then, the borrower decides to retire the bond. If the call premium is one year's interest, 10%, you'll get a check for the bond's face amount ($1,000) plus the premium ($100). In relation to the ...
ICE BofA Euro High Yield Index Effective Yield - St. Louis Fed Qualifying securities must have at least one year remaining term to maturity, a fixed coupon schedule, and a minimum amount outstanding of Euro 100 million. Original issue zero coupon bonds, "global" securities (debt issued simultaneously in the eurobond and euro domestic markets), 144a securities and pay-in-kind securities, including toggle ... VANGUARD EXTENDED DURATION TREASURY INDEX FUND ETF SHARES ... - Insider Vanguard Extended Duration Treasury Index Fund Institutional Plus Shares. -31.86. PIMCO 25+ Year Zero Coupon U.S. Treasury Index Exchange-Traded Fund. -31.84. iShares 25+ Year Treasury STRIPS Bond ... ICE BofA US Corporate Index Effective Yield (BAMLC0A0CMEY) Each security must have greater than 1 year of remaining maturity, a fixed coupon schedule, and a minimum amount outstanding of $250 million. Original issue zero coupon bonds, "global" securities (debt issued simultaneously in the eurobond and US domestic bond markets), 144a securities and pay-in-kind securities, including toggle notes, qualify ... Zero Coupon Bonds: Calculating Price, Interest, and Value - BrainMass The bond has a coupon rate of 6.4%, pays interest annually, has a face value of $1,000, 4 years to maturity, and a yield to maturity of 7.2%. The bond's duration is 3.6481 years. You expect that interest rates will fall by .3% later today. * Use the modified duration to find the approximate percentage change in the bond's price.
Calculate the price of a zero-coupon bond that matures in 16 years if ...
Types Of Different Bonds - Bond Fundamentals Bonds are often issued by corporations and governments, and investors purchase them as a form of savings and security.These bonds have a maturity date, and once that date is reached, the issuing corporation must repay the investor along with a portion of the profit. Brokers handle transactions involving bonds between the issuer and the investor.

Macaulay's Duration, a Second Look - GlynHolton.com
South Africa Government Bonds - Yields Curve 10 Years vs 2 Years bond spread is 339 bp. Normal Convexity in Long-Term vs Short-Term Maturities. Central Bank Rate is 5.50% (last modification in July 2022). The South Africa credit rating is BB-, according to Standard & Poor's agency. Current 5-Years Credit Default Swap quotation is 313.76 and implied probability of default is 5.23%.
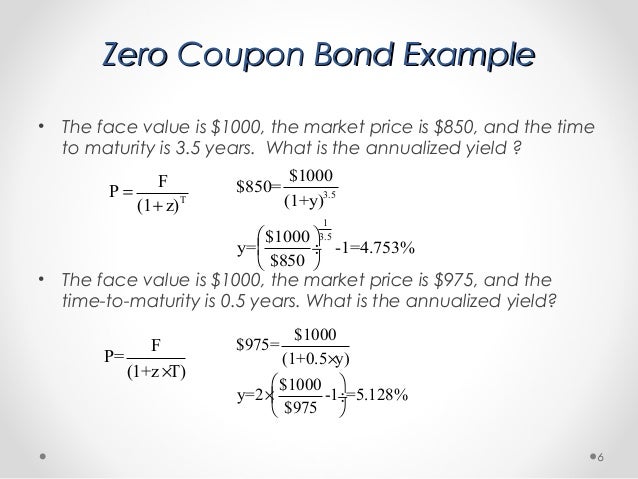
Bonds part 1
Zero Coupon 2025 Fund | American Century Investments DURATION Due to rounding, these values may exceed 100% as of 07/31/2022 Management Robert Gahagan Senior Vice President, Senior Portfolio Manager Jim Platz, CFA Vice President, Portfolio Manager Miguel Castillo Vice President, Portfolio Manager Invest Now Put your strategy into action. Buy This Fund

Zero-coupon bond - PrepNuggets
Active, Index & Smart Beta Exchange Traded Funds (ETFs) | PIMCO The 25+ Year Zero Coupon U.S. Treasury Index Exchange-Traded Fund was rated against the following numbers of Long Government funds over the following time periods: 1 stars out of 30 funds overall; 1 stars out of 30 funds in the last three years, 1 stars out of 27 funds in the last five years, and 1 star out of 21 funds in the last ten years.

Current Zero Coupon Bond Rates vs Historical
EDV Vanguard Extended Duration Treasury ETF - Seeking Alpha It primarily invests in extended duration zero coupon U.S. Treasury securities with maturities between 20 and 30 years. ... U.S. Treasury STRIPS 20-30 Year Equal Par Bond Index of extended ...
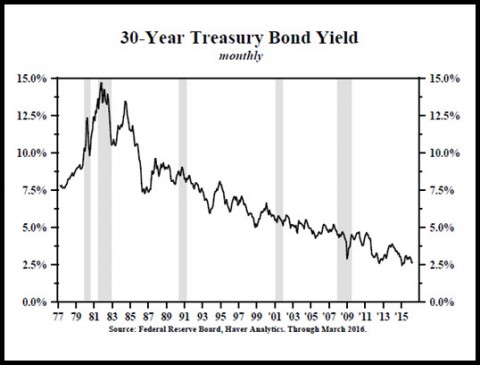
Thoughts on Duration
ICE BofA US High Yield Index Option-Adjusted Spread Each security must have greater than 1 year of remaining maturity, a fixed coupon schedule, and a minimum amount outstanding of $100 million. Original issue zero coupon bonds, "global" securities (debt issued simultaneously in the eurobond and US domestic bond markets), 144a securities and pay-in-kind securities, including toggle notes, qualify ...
PPT - Chapter 12 Bond Prices and the Importance of Duration PowerPoint ...
iShares 7-10 Year Treasury Bond ETF | IEF - BlackRock The iShares 7-10 Year Treasury Bond ETF (IEF) seeks to track the investment results of an index composed of U.S. Treasury bonds with remaining maturities between seven and ten years.

zero-coupon bond | zero-coupon bond on calculator. Please fe… | Flickr
Finance Archive | September 04, 2022 | Chegg.com Find the duration of a 6% coupon bond making annual coupon payments if it has three years until maturity and a yield to maturity of 6%. b. What is the duration if the yield to maturity is 10%? ... We know that the 6 month zero bond price is $94.9; the 1 year coupon bond price is $90.0 with semi-annual coupon rate 4%; the 1.5 year coupon bond ...

Coupon Yield Formula ~ Coupon Two
› dictionary › dWhat Is Duration of a Bond? - TheStreet Definition - TheStreet Mar 22, 2022 · Zero-Coupon Bonds. The easiest duration to calculate is that of a zero-coupon bond. This bond has zero yield, which means it does not pay any interest. Its duration is equal to its time to maturity.

Zero Coupon Bonds Explained - Fervent | Finance Courses, Accounting Courses
› news › businessMC Explains | What is a 'zero-coupon, zero-principal' instrument? Jul 20, 2022 · The government has cleared 'zero-coupon, zero-principal' instruments for listing as securities on the social stock exchanges. ... it will come with a time duration. “These bonds will carry a ...

Should I Invest in Zero Coupon Bonds?
› dv01DV01 (Definition, Formula) | How to Calculate Dollar Duration ... DV01 simple calculation assumes that Bonds pay fixed coupon payments at regular intervals; however, there are certain categories of Bonds such as Floating Rate Bonds, Zero Coupon Bonds Zero Coupon Bonds In contrast to a typical coupon-bearing bond, a zero-coupon bond (also known as a Pure Discount Bond or Accrual Bond) is a bond that is issued ...
A zero-coupon bond pays $1000 in ten years and sells for $400 today ...
What Is Duration In Finance? - Investopedia The modified duration of a bond with semi-annual coupon payments can be found with the following formula: ModD=\frac {\text {Macaulay Duration}} {1+\left (\frac {YTM} {2}\right)} M odD = 1+( 2Y T...
What Are Zero Coupon Bonds? - Annuity.com
› chapter-13Accounting For Bonds Payable - principlesofaccounting.com To further explain, the interest amount on the $1,000, 8% bond is $40 every six months. Because the bonds have a 5-year life, there are 10 interest payments (or periods). The periodic interest is an annuity with a 10-period duration, while the maturity value is a lump-sum payment at the end of the tenth period.
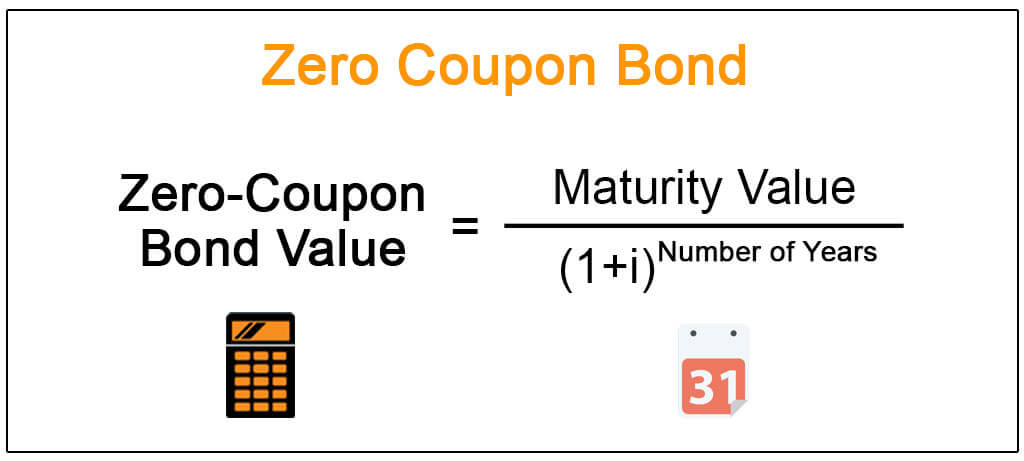
Zero Coupon Bond (Definition, Formula, Examples, Calculations)
› terms › cCoupon Definition - Investopedia Apr 02, 2020 · Coupon: The annual interest rate paid on a bond, expressed as a percentage of the face value.

Zero-Coupon Bond Funds Definition How to Invest
United Kingdom Government Bonds - Yields Curve 10 Years vs 2 Years bond spread is -25.2 bp. Yield Curve is inverted in Long-Term vs Short-Term Maturities. Central Bank Rate is 1.75% (last modification in August 2022). The United Kingdom credit rating is AA, according to Standard & Poor's agency. Current 5-Years Credit Default Swap quotation is 25.60 and implied probability of default is 0.43%.
Post a Comment for "39 zero coupon bonds duration"